Here’s how to buy crypto in Canada in short: use a platform registered with Canadian securities regulators, fund it with Interac e-Transfer, and place your order, ideally as a limit order to keep fees down. The main choice is between an investing app you may already use, like Wealthsimple, and a dedicated exchange such as Kraken, Coinbase, Shakepay, Newton or Bitbuy.
Canada also has a few rules that other countries don’t: a registration regime for crypto platforms, an annual purchase limit on many coins for retail investors, and the option of holding bitcoin through an ETF inside a TFSA or RRSP. This guide covers all three, along with the costs of the main options.
Step 1: Use a registered platform
After several platform failures, Canadian securities regulators required crypto trading platforms serving Canadians to register or sign formal commitments while they complete registration. The Canadian Securities Administrators (CSA) keep a list of authorized platforms, and provincial regulators publish their own, such as the Ontario Securities Commission’s list.
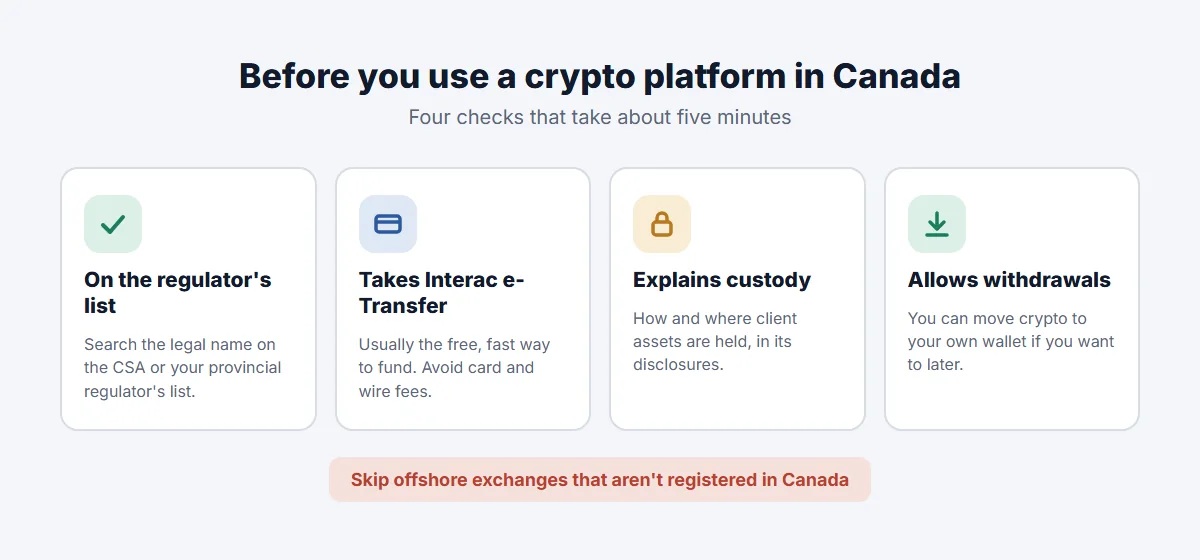
Before you open an account:
- Search the platform’s name on the CSA or your provincial regulator’s list. Use the exact legal entity name from the platform’s terms.
- Check how it holds your assets. Registered platforms must keep client assets with qualified custodians and explain this in their disclosures.
- Make sure you can withdraw to your own wallet if you plan to self-custody later.
- Avoid platforms on regulators’ warning lists. Large offshore exchanges that aren’t registered can freeze or close Canadian accounts with little notice.
Step 2: Compare the main options
| Platform | How you buy | Published cost | Good for |
|---|---|---|---|
| Wealthsimple | Simple app inside your investing account | Flat 0.5% fee plus a spread; limit orders have no spread; $1 surcharge on orders under $100 | People who already invest with Wealthsimple |
| Kraken | Kraken app or Kraken Pro order book | Pro: 0.40% maker / 0.80% taker at entry tier; instant buy 1% plus spread | Lower fees once you use Kraken Pro |
| Coinbase | Simple buy or Coinbase Advanced | Simple buy: spread plus fee; Advanced: tiered maker/taker | A familiar global brand |
| Shakepay, Newton, Bitbuy | Simple Canadian apps | Mostly spread-based pricing; check the quote | Straightforward buying in Canadian dollars |
Costs come from Wealthsimple’s crypto page and Kraken’s fee schedule as published in November 2026. Spread-based apps don’t publish a fixed rate, so compare the amount of crypto you’d receive for the same dollars on two apps before deciding.
A few things worth knowing:
- The order type matters as much as the app. On Wealthsimple, a limit order avoids the spread. On Kraken, Kraken Pro’s limit orders are much cheaper than instant buys. Crypto exchange fees explained covers how spreads and maker and taker fees work.
- Coin selection is narrower in Canada than on global exchanges, and it varies by platform. Some stablecoins, notably USDT, aren’t offered on Canadian registered platforms under the CSA’s rules.
- Deposit method matters. Check whether the platform takes Interac e-Transfer for free. Card purchases and wire transfers can add significant costs.
If you’re deciding between two global names, Coinbase vs Kraken compares them in more detail.
Step 3: Open and secure your account
Sign up from the official app or website, verify your identity, and turn on two-factor authentication with an authenticator app rather than SMS. How to buy crypto safely for the first time walks through the security settings in detail.
During sign-up, Canadian platforms also ask about your income, investment experience and assets. That’s part of their registration obligations: the answers decide which category of investor you fall into and how much you can buy of certain coins.
The $30,000 annual limit
For most retail investors, Canadian platforms apply a $30,000 limit on net purchases over a rolling 12 months of crypto assets that aren’t on the exempt list. Bitcoin, ether and certain stablecoins are typically exempt, so the limit mostly affects smaller altcoins. Investors who meet higher income or asset thresholds get higher limits, and the cap applies per platform.
For most beginners buying bitcoin and ether, the limit never comes into play. If it does, it’s a sign you’re putting a large amount into riskier coins, which is worth pausing over anyway. What are altcoins? explains why.
Step 4: Fund with Interac e-Transfer and buy
Interac e-Transfer is the most common way to fund a Canadian crypto account, and it’s usually free and quick. Once the money arrives:
- Choose the coin and enter the amount in Canadian dollars.
- Use a limit order where the app offers one, set at or just below the current price.
- Check the total cost and the amount of crypto you’ll receive before confirming.
New platforms may hold freshly deposited funds or purchases for a few days before you can withdraw them. That’s a normal anti-fraud measure.
Step 5: Decide where to keep it
Small amounts can stay on a registered platform with two-factor authentication. For larger, long-term holdings, a hardware wallet removes the platform risk. Best crypto wallets for beginners compares the options, and is it safe to keep crypto on an exchange? explains the risks of leaving it.
Buying crypto directly vs a crypto ETF in a TFSA
Canada was one of the first countries to approve spot bitcoin ETFs, in February 2021, and there are now bitcoin and ether ETFs on the Toronto Stock Exchange. You buy them through any brokerage account, including a TFSA or RRSP.
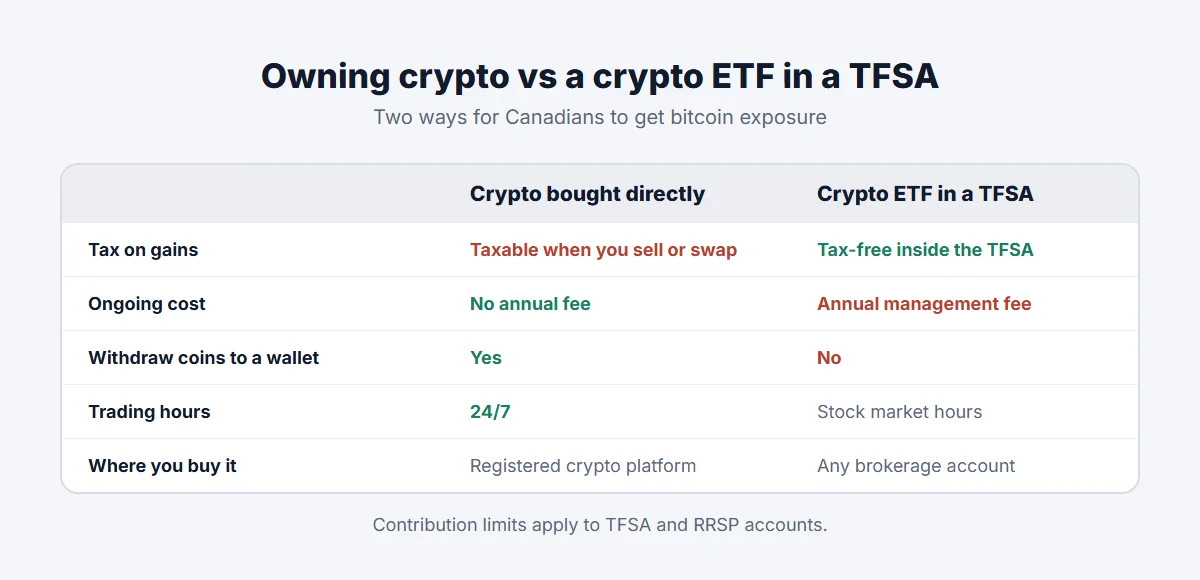
That makes a real difference for some investors:
- Crypto bought directly can’t be held in a TFSA or RRSP. Gains when you sell are taxable, and you can withdraw the coins to your own wallet.
- A crypto ETF in a TFSA grows tax-free, but you pay an annual management fee, you can’t withdraw actual coins, and it trades only during market hours.
If you want long-term bitcoin exposure and have unused TFSA room, an ETF may be the more efficient route. If self-custody or using crypto matters to you, buy it directly. How bitcoin ETFs work explains the structure in more detail.
Taxes on crypto in Canada
The Canada Revenue Agency treats crypto as a commodity, not currency. For most people, selling, swapping or spending crypto produces a capital gain or loss, and half of a capital gain is included in taxable income. If your activity looks like a business, such as frequent trading, gains can be taxed in full as business income.
Keep records of every purchase in Canadian dollars, including fees, because you’ll need them to work out your adjusted cost base. The CRA’s guide for crypto-asset users explains what to report, and our crypto taxes guide covers the general principles.
How to buy crypto in Canada: quick checklist
- The platform is on the CSA or your provincial regulator’s list.
- You fund with Interac e-Transfer, not a card.
- You use limit orders where available.
- You know whether the $30,000 limit affects the coins you want.
- You’ve considered whether a TFSA ETF suits your goal better than owning coins.
- You keep your own record of every purchase for tax.